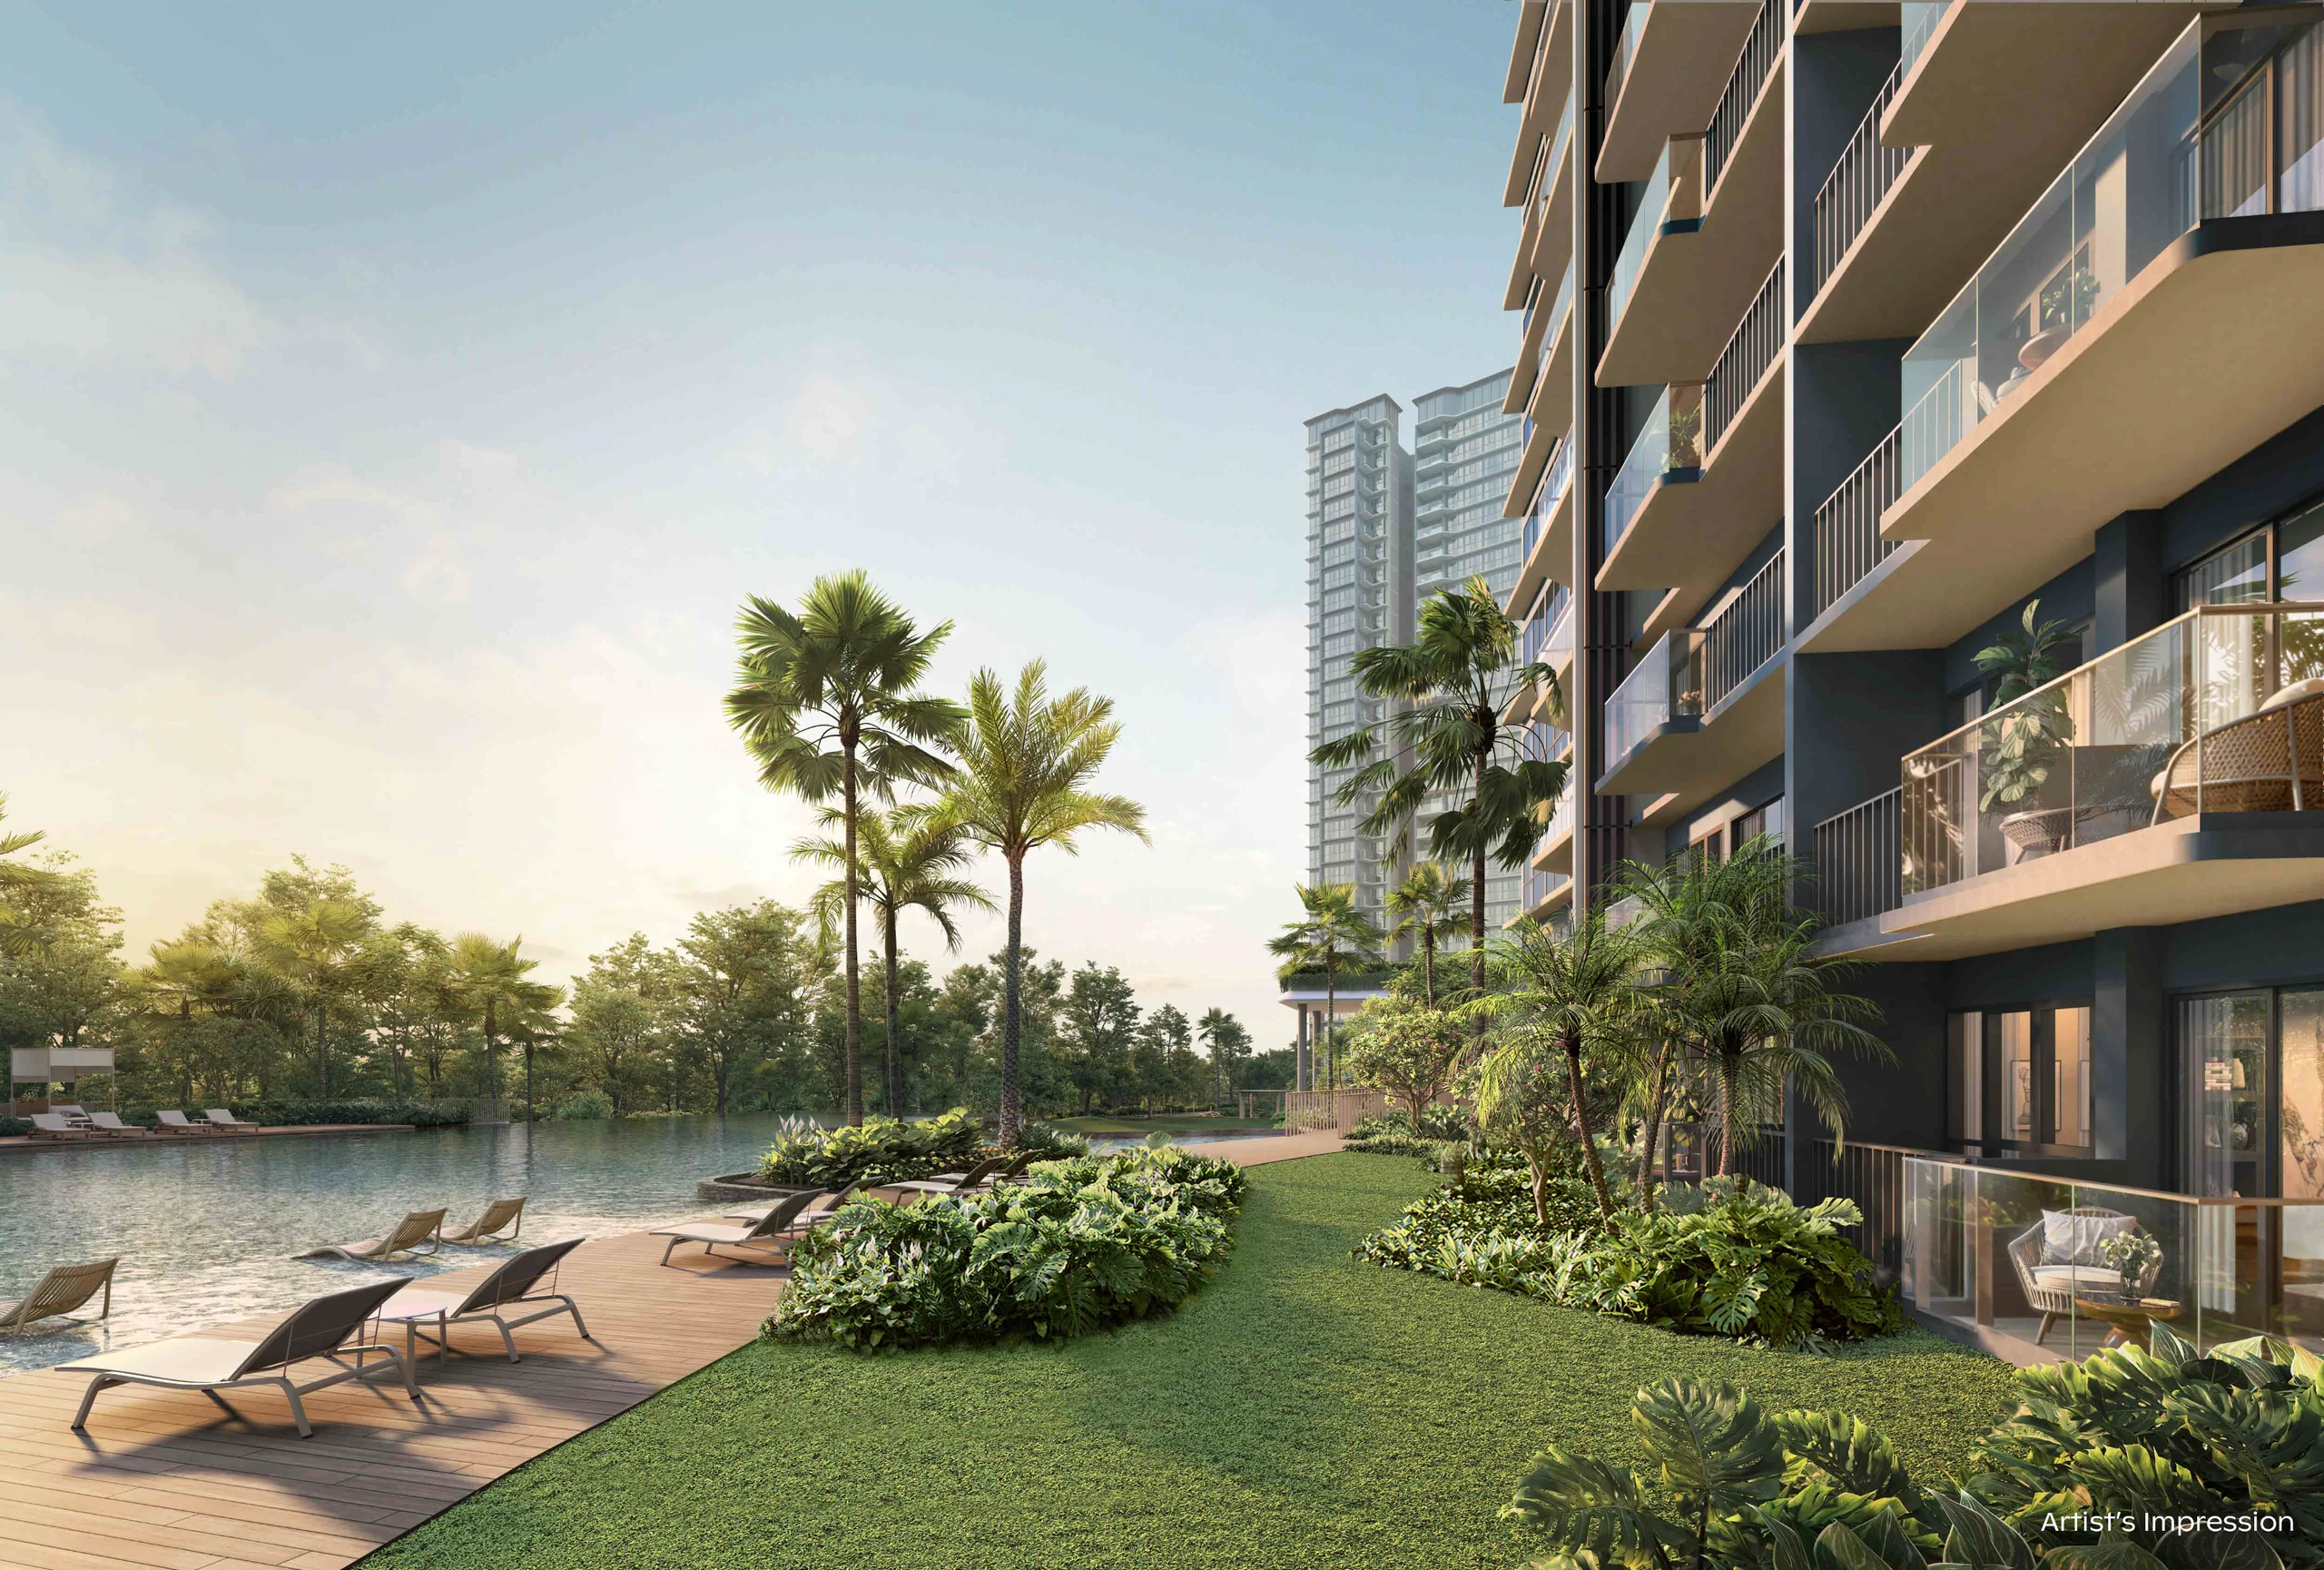
Thomson Reserve official architectural impression: View Out from PES towards the internal biological sanctuary
What Is the New Launch Condo Buying Process in Singapore?
Buying a new launch condo in Singapore follows a structured 8-step process: (1) Obtain an In-Principle Approval (IPA) from a bank to confirm your budget; (2) Register for VVIP priority access with the developer's sales team; (3) Attend the showflat preview and shortlist units; (4) On booking day, pay a 5% option fee to secure your unit; (5) Within 8 weeks, sign the Sales & Purchase Agreement and pay 15% (less the booking fee); (6) During construction, make progressive payments as milestones are reached; (7) At TOP (Temporary Occupation Permit), collect keys and conduct a defect inspection; (8) After the defects liability period, receive the CSC (Certificate of Statutory Completion). For Thomson Reserve, this entire journey spans approximately 3–4 years from booking in late 2026 to key collection around 2030. Thomson Reserve has launched; 125 units are left as of 2 Nov 2026, and the bounce list for 2-Bedroom + Study, 3- and 4-bedroom layouts is open.
In This Guide
- 1Step 1: Get Your In-Principle Approval (IPA) Before You Start
- 2Step 2: VVIP Registration and Why Early Matters
- 3Step 3: Showflat Viewing and What to Look For
- 4Step 4: Booking Day and Securing Your Unit
- 5Step 5: Signing the Sales & Purchase Agreement
- 6Step 6: Understanding Stamp Duties (BSD & ABSD)
- 7Step 7: TDSR and How Much You Can Actually Borrow
- 8Step 8: The Progressive Payment Scheme Explained
- 9Step 9: TOP, Defects Inspection & Key Collection
- 10Step 10: Common Mistakes to Avoid
- 11Frequently Asked Questions
Step 1: Get Your In-Principle Approval (IPA) Before You Start
The single most important step before visiting any showflat is obtaining an In-Principle Approval (IPA) from a bank. An IPA is a conditional commitment from a lender stating how much they are willing to lend you based on your income, existing debts, credit history, and the current TDSR regulations. Without an IPA, you are guessing your budget, and in a high-demand project like Thomson Reserve, that could mean missing your preferred unit.
To obtain an IPA, you will need: your latest 3 months of payslips or CPF contribution statements (for employed individuals), your latest 2 years of Notice of Assessment from IRAS (for self-employed individuals), your CPF statement showing Ordinary Account balance, and details of any existing loans (car loans, existing mortgages, personal loans). Most banks issue an IPA within 3–5 business days, and it is typically valid for 30–90 days.
A practical tip: apply for IPAs from 2–3 banks to compare rates and loan packages. Do not just look at the headline interest rate, compare the lock-in period (typically 2–3 years), early repayment penalties, and whether the rate is fixed or floating (SORA-pegged). In the current rate environment (as of 15 October 2026), fixed-rate packages at about 2% are competitive, and building-under-construction (BUC) packages at around 1.5% can lower repayments further during the construction period.
Step 2: VVIP Registration and Why Early Matters
VVIP registration is your gateway to priority access before the public launch. When you register with the developer's appointed sales representative (like Law Viona for Thomson Reserve), your name is placed on a priority list that grants you: first access to the showflat before it opens to the general public, priority unit selection on booking day, any preferential pricing the developer offers before public launch, and direct updates on floor plan releases, pricing, and project milestones.
Thomson Reserve shows why registering early matters. The project has launched: the showflat opened on 17 October 2026, Priority Sales booking day was 30 October 2026, and every 3-Bedroom and 4-Bedroom layout sold out that weekend. The developers, UOL, CapitaLand and SingLand, have a proven track record of strong launch-day absorption; AMO Residence, by two of the same developers, sold 98% of units on launch day in 2022. Thomson Reserve has launched; 125 units are left as of 2 Nov 2026, and the bounce list for 2-Bedroom + Study, 3- and 4-bedroom layouts is open.
What you can still do at Thomson Reserve
- Get the list of the 125 available units (2-Bedroom from S$1.635M, 2-Bedroom Premium from S$1.873M, 5-Bedroom Suite from S$5.079M) via the balance units chart
- Book a showflat appointment to view the remaining stacks and facings
- Join the bounce-unit list for sold-out 2-Bedroom + Study, 3- and 4-Bedroom layouts
- Direct updates from Law Viona of PropNex on current prices
- Personalised unit recommendation based on your budget
Step 3: Showflat Viewing and What to Look For
The showflat is a carefully constructed sales environment. Understanding what to look for will help you make an informed decision. The displayed unit is typically a "type unit" with premium fittings that may not be included in the base price. Pay attention to: the actual dimensions of each room (bring a measuring tape), the ceiling height, the positioning of air-con ledges and bomb shelters, the natural light direction (morning sun vs afternoon sun), and the view from the balcony, which will be simulated but should be verified against the site plan, along with the facilities and amenity spaces shown on the scale model.
For Thomson Reserve, the most critical decision is stack selection. Units facing the Central Catchment Nature Reserve and MacRitchie Reservoir command a premium but hold their value better long-term, these views are permanently protected under URA zoning and cannot be built over. Road-facing units are more affordable but may experience traffic noise from Bright Hill Drive. Higher-floor units generally appreciate faster than lower-floor units, particularly in projects where the view is the primary differentiator.
Checklist: What to Bring
- - IPA from your bank
- - NRIC or passport
- - Chequebook (for booking fee)
- - Measuring tape
- - List of preferred unit numbers
Checklist: What to Ask
- - What is included in the base price vs optional?
- - Which stacks face the reservoir?
- - What is the maintenance fee estimate?
- - When is the expected TOP date?
- - What are the differential premiums for higher floors?
Step 4: Booking Day and Securing Your Unit
Booking day is the most critical 24 hours in the new launch process. VVIP registrants are invited to book before the general public, typically in order of registration priority. When your turn arrives, you will select your unit from the available inventory, complete the Option to Purchase (OTP) form, and pay a 5% booking fee (cashier's order or cheque only, no cash or credit card). The OTP grants you the exclusive right to purchase that unit for 21 days.
The booking fee is non-refundable if you decide not to proceed. However, it is applied toward your total purchase price. For a S$2 million unit at Thomson Reserve, the 5% booking fee is S$100,000. Make sure you have the cash ready. Many buyers have missed their preferred unit because they could not produce a cashier's order on the spot.
A booking-day tip: arrive early, bring multiple blank cashier's orders in different amounts (in case your first-choice unit is taken), and have a ranked list of 5–10 preferred unit numbers. The best units, high floors with reservoir views, pool-facing mid-levels, and corner units, are typically absorbed within the first few hours.
Step 5: Signing the Sales & Purchase Agreement
Within 8 weeks of booking, you must sign the Sales & Purchase Agreement (S&P) and pay the balance of the downpayment to reach 20% of the purchase price (less the 5% booking fee already paid). For a S$2 million unit, this means paying an additional S$300,000 at S&P signing. This can be funded from CPF Ordinary Account savings, cash, or a combination of both.
The S&P is a legally binding contract prepared by the developer's lawyers. It sets out the full terms of the sale, including the unit specifications, payment schedule, TOP date (including penalties for late delivery, typically S$100–S$300 per day depending on unit size), defect liability period (usually 12 months from TOP), and the list of fittings and finishes included in the purchase price. Your lawyer should review the S&P before you sign, if you do not have a lawyer, the developer can recommend one, or you can engage your own conveyancing lawyer.
Step 6: Understanding Stamp Duties (BSD & ABSD)
Stamp duties are payable within 14 days of signing the S&P. There are two components: Buyer's Stamp Duty (BSD) and Additional Buyer's Stamp Duty (ABSD). BSD applies to all buyers regardless of nationality, while ABSD depends on your residency status and property ownership count.
| Stamp Duty Type | Rate | Example (S$2M Unit) |
|---|---|---|
| BSD (1st tier) | 1% on first S$180,000 | S$1,800 |
| BSD (2nd tier) | 2% on next S$180,000 | S$3,600 |
| BSD (3rd tier) | 3% on next S$640,000 | S$19,200 |
| BSD (4th tier) | 4% on amount above S$1M | S$40,000 |
| Total BSD | Tiered up to 4% | S$64,600 |
ABSD Rates 2026
- Singapore Citizen, 1st property0%
- Singapore Citizen, 2nd property20%
- Singapore Citizen, 3rd and beyond30%
- Permanent Resident, 1st property5%
- Permanent Resident, 2nd and beyond30%
- Foreigner: Any property60%
Step 7: TDSR and How Much You Can Actually Borrow
The Total Debt Servicing Ratio (TDSR) is the most important regulatory constraint on your borrowing power. Introduced by MAS in 2013 and tightened over subsequent years, the TDSR rule states that your total monthly debt obligations cannot exceed 55% of your gross monthly income. Note that banks use a stress-test interest rate of 4% (not the actual loan rate) to calculate whether you pass the TDSR threshold.
Here is a practical example: if your gross monthly income is S$15,000 and you have an existing car loan of S$1,200/month, your maximum allowable total debt is S$8,250 (55% of S$15,000). Subtracting the car loan leaves S$7,050 for the mortgage. At the 4% stress-test rate over a 25-year tenure, this supports a maximum loan of approximately S$1.34 million, meaning you can purchase a property up to roughly S$1.78 million (at 75% LTV). For a S$2 million unit, you would need a higher income or a larger downpayment to bridge the gap.
TDSR Calculation Example
Gross monthly income: S$15,000
55% TDSR limit: S$8,250/month
Existing car loan: S$1,200/month
Available for mortgage: S$7,050/month
Maximum loan (4% stress, 25 years): ~S$1.34M
Maximum property price (75% LTV): ~S$1.79M
Step 8: The Progressive Payment Scheme Explained
The Progressive Payment Scheme (PPS) is one of the biggest advantages of buying a new launch over a resale property. Instead of paying the full purchase price upfront and starting full mortgage repayments immediately, you pay in tranches tied to construction milestones. This significantly improves your cash flow during the 3–4 year construction period.
| Milestone | Payment | Cumulative |
|---|---|---|
| Booking (OTP) | 5% | 5% |
| S&P Signing (within 8 weeks) | 15% | 20% |
| Foundation completion | 10% | 30% |
| Reinforced framework | 10% | 40% |
| Partition walls | 5% | 45% |
| Ceiling / roofing | 5% | 50% |
| Door / window frames | 5% | 55% |
| Car park / roads / drainage | 5% | 60% |
| TOP (Temporary Occupation Permit) | 25% | 85% |
| CSC (Statutory Completion) | 15% | 100% |
For a S$2 million unit at Thomson Reserve, your mortgage starts at approximately S$1.5 million (75% LTV). In the first year, you only pay interest on the disbursed amount, not the full loan. At foundation completion (30% paid), your loan disbursement is roughly S$450,000, meaning your monthly repayment is approximately S$1,500–S$1,800 at current rates. The repayments grow gradually as construction progresses, giving you time to adjust your finances before the full mortgage kicks in at TOP.
Step 9: TOP, Defects Inspection & Key Collection
The Temporary Occupation Permit (TOP) is the milestone every buyer waits for. It means the building is structurally complete and safe for occupation, and you can finally collect your keys. For Thomson Reserve, TOP is expected around 2030, approximately 3–4 years from the October 2026 launch. Upon TOP, the final 25% of the purchase price is due, and your mortgage reaches its full monthly repayment amount.
Within 7 days of collecting your keys, you should conduct a thorough defects inspection. The developer provides a 12-month Defects Liability Period (DLP) during which they are obligated to repair any defects at no cost. Common defects to check for: uneven floor tiles, scratches on countertops, misaligned cabinet doors, water pressure issues, air-conditioning coolant leaks, and paint imperfections. Document every issue with photographs and submit the defects list to the developer's Customer Service Unit (CSU) promptly.
Step 10: Common Mistakes to Avoid
Not getting an IPA first
Falling in love with a unit you cannot finance is emotionally and financially costly. Always secure your IPA before viewing showflats.
Underestimating total costs
Beyond the purchase price, budget for BSD (S$64,600 on S$2M), ABSD (if applicable), legal fees (~S$3,000), valuation fees, and renovation costs.
Ignoring the view orientation
A west-facing unit may be cheaper but will be unbearably hot in the afternoons. Morning sun (east-facing) is generally preferred in Singapore.
Buying based on showflat alone
The showflat uses scaled-down furniture and premium fittings that may not be included. Always verify actual dimensions and the fittings list in the S&P.
Not reviewing the S&P carefully
The S&P contains critical terms about late delivery penalties, defects liability, and unit specifications. Engage a lawyer to review it before signing.
Forgetting about maintenance fees
Conservancy charges for large developments with many facilities can be S$400–600/month. Factor this into your monthly budget from day one.
Frequently Asked Questions
What is VVIP registration for a new launch condo?
VVIP (Very Very Important Person) registration allows buyers to register their interest with the developer's appointed sales team before the public launch. VVIP registrants typically receive priority access to the showflat, first pick of available units, and sometimes preferential pricing before the public launch. Thomson Reserve has launched; 125 units are left as of 2 Nov 2026, and the bounce list for 2-Bedroom + Study, 3- and 4-bedroom layouts is open. Buyers can still request the available-unit list, book a showflat appointment and join the bounce list.
How much stamp duty do I pay when buying a new launch condo in Singapore?
Buyers pay two types of stamp duty. Buyer's Stamp Duty (BSD) is tiered: 1% on the first S$180,000, 2% on the next S$180,000, 3% on the next S$640,000, and 4% on amounts above S$1 million. Additional Buyer's Stamp Duty (ABSD) depends on your residency status: Singapore Citizens pay 0% for their first property, 20% for the second, and 30% for the third and beyond. Permanent Residents pay 5% for the first property and 30% for the second. Foreigners pay 60% on any residential property.
What is the progressive payment scheme for new launch condos?
The Progressive Payment Scheme (PPS) allows buyers of under-construction properties to pay in instalments tied to construction milestones. You pay 5% booking fee upon signing the Option to Purchase, 15% within 8 weeks upon signing the Sales & Purchase Agreement, and the remaining 80% is disbursed in 5–10% tranches as construction progresses. Your mortgage repayments start small and increase gradually, improving cash flow compared to resale purchases.
What is TDSR and how does it affect my condo purchase?
TDSR (Total Debt Servicing Ratio) is a regulatory limit set by MAS. Your total monthly debt obligations, including the new mortgage, car loans, credit card debts, and other loans, cannot exceed 55% of your gross monthly income. Banks use a stress-test interest rate of 4% to calculate your TDSR. If your TDSR exceeds 55%, you will need to reduce your loan amount or pay down existing debts before qualifying.
Should I get an In-Principle Approval (IPA) before viewing showflats?
Yes, obtaining an IPA from a bank before viewing showflats is strongly recommended. An IPA confirms how much you can borrow based on your income, debts, and credit profile. It prevents the disappointment of selecting a unit you cannot finance. Thomson Reserve has launched; 125 units are left as of 2 Nov 2026, and the bounce list for 2-Bedroom + Study, 3- and 4-bedroom layouts is open, so having an IPA ready lets you act quickly on an available unit or a bounced one. The IPA is typically valid for 30–90 days.
How long does it take from booking to receiving keys for a new launch condo?
The timeline from booking to key collection for a new launch condo is typically 3–4 years. For Thomson Reserve (expected TOP ~2030): (1) Showflat viewing (showflat opened 17 October 2026); (2) Booking day (Priority Sales was 30 October 2026; remaining units book by appointment), pay 5% option fee; (3) Within 8 weeks, sign S&P and pay 15%; (4) Construction period, progressive payments; (5) TOP ~2030, collect keys; (6) CSC typically 6–12 months after TOP.
Important Disclaimer
This guide is prepared for informational and educational purposes only. It does not constitute financial advice, investment recommendations, or legal guidance. The stamp duty rates, TDSR thresholds, and financing rules described are accurate to the best of our knowledge as of 2026-11-04, but regulations may change. There may be errors or omissions in this article. Always perform your own due diligence and consult licensed professionals, financial advisors, mortgage bankers, and conveyancing lawyers, before committing to any property purchase. If you have questions or need clarification on any aspect of the buying process, contact Law Viona for a free consultation via WhatsApp at +65 9835 5552.
Thomson Reserve: 125 units left
- 2-Bedroom33 left
- from S$1.635MS$2,762 psf
- 2-Bedroom Premium90 left
- from S$1.873MS$2,763 psf
- 5-Bedroom Suite (Private Lift)2 left
- from S$5.079MS$2,809 psf
2-Bedroom + Study, 3- and 4-bedrooms are sold out; the bounce-unit list is open. Prices and availability updated , subject to change. Handled by Law Viona (PropNex, CEA R055553G), with no commission payable by buyers.
See every unit on the price chartGet the available-unit list & prices
All 125 remaining units with stack-by-stack prices, sent to your WhatsApp. The e-brochure and floor plans download straight after.
About the Author
Law Viona assists prospective buyers with enquiries for Thomson Reserve. For project information or to register your interest, contact Law Viona via WhatsApp at +65 9835 5552. Please refer to the footer for full marketing agent disclosure and terms.